
Tokenised assets face institutional tests on liquidity
Fri, 30th Oct 2026 (Today)
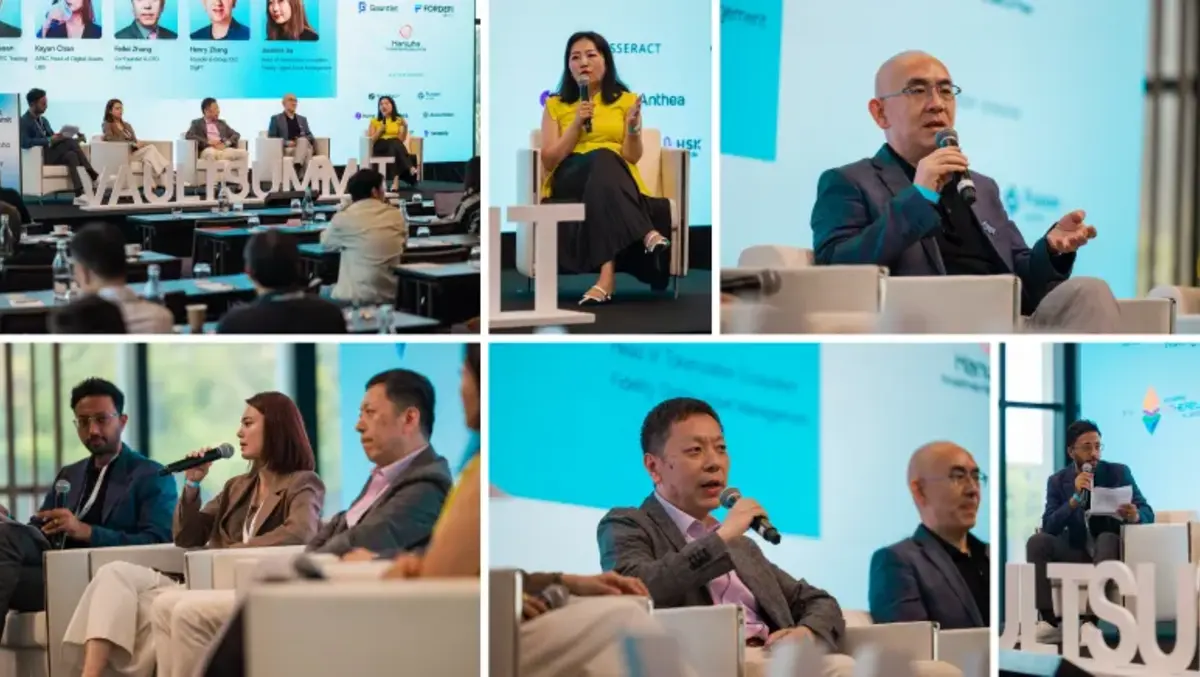
DigiFT has published insights from a Vault Summit Singapore panel on the use of tokenised assets in institutional investment strategies. The discussion focused on how institutions decide whether on-chain uses of assets are suitable for capital allocation.
The panel examined the shift from simply issuing tokenised fund interests to using those holdings in financing, collateral and portfolio construction. It brought together participants from asset management, banking, digital assets and market infrastructure to discuss the conditions institutions apply before committing capital.
A central theme was that an acceptable underlying asset does not automatically make every strategy built around it investable. Once a fund holding is pledged as collateral, borrowed against or combined with other positions, an institution is no longer assessing only the asset itself but the full exposure created by the strategy.
That distinction matters for mandates and risk limits. An institution may be comfortable owning a fund directly, while rejecting a leveraged structure linked to the same fund because the financing and reinvestment elements change the nature of the exposure.
Liquidity questions
Liquidity was another focus. The panel noted that tokenisation may improve the on-chain transferability of a fund holding, but it does not necessarily change the redemption timetable of the underlying fund. A token may therefore move outside market hours while the underlying asset remains subject to conventional withdrawal schedules.
For institutions, this creates a practical issue when a strategy requires cash before redemptions can be processed. In such cases, allocators need to determine whether another source of liquidity is available and whether it would remain reliable under stress.
The discussion also addressed the role of curation in digital asset markets. Once assets are assembled into a portfolio or strategy, decisions must be made on selection, weightings and rebalancing. Those tasks can resemble traditional investment management even when presented through an on-chain structure.
According to the published takeaways, institutions need to distinguish between a provider that offers software for investors to manage their own portfolios and one that makes investment decisions on an ongoing basis. The label of curation can cover both models, but the responsibilities and oversight requirements differ.
Responsibility split
This difference affects which party controls investment choices and which retains accountability. It also raises questions about whether a provider is acting only as a technology supplier or undertaking functions that amount to portfolio management.
That issue becomes more significant for institutional investors that must define delegated authority and governance standards before allocating funds. A technical description of a platform does not, on its own, answer questions about responsibility for the decisions made within it.
Another part of the discussion focused on the safeguards institutions require before moving activity on-chain. More efficient settlement or collateral use may offer an incentive, but those benefits do not remove the need for clear claims on assets, governance processes and reliable reporting.
Smart contracts and wallet access were identified as additional operational considerations. Institutions assessing tokenised strategies must account for these risks alongside more familiar concerns such as custody, reporting and continuity during periods of market disruption.
From pilot to scale
The panel also argued that a successful pilot should not be treated as sufficient evidence for a larger institutional allocation. Investors need proof that a strategy can operate at the intended size, meet withdrawal terms and continue functioning during disruption, rather than relying on a limited demonstration.
Operational records, transaction data and reporting history were cited as the forms of evidence institutions use to assess whether a structure is ready for broader use. This reflects a wider market shift, with tokenised asset products increasingly judged not only on technical design but also on whether they meet the standards applied to more established investment channels.
Among those featured in the discussion were Henry Zhang, Founder and Group Chief Executive Officer of DigiFT; Feifei Zhang, Co-Founder, Chief Financial Officer and Chief Investment Officer of Anthea; Jasmine J., Head of Tokenisation Ecosystem at Fidelity Digital Asset Management; and Ka Yan Chan, who leads digital assets for UBS in Asia-Pacific. The session was moderated by Aravind Srinivasan, who leads GSR's systematic over-the-counter business.
The published conclusions said that, for tokenised assets to attract institutional capital, market participants need to explain who makes investment decisions, how liquidity works and what the operating record shows.