

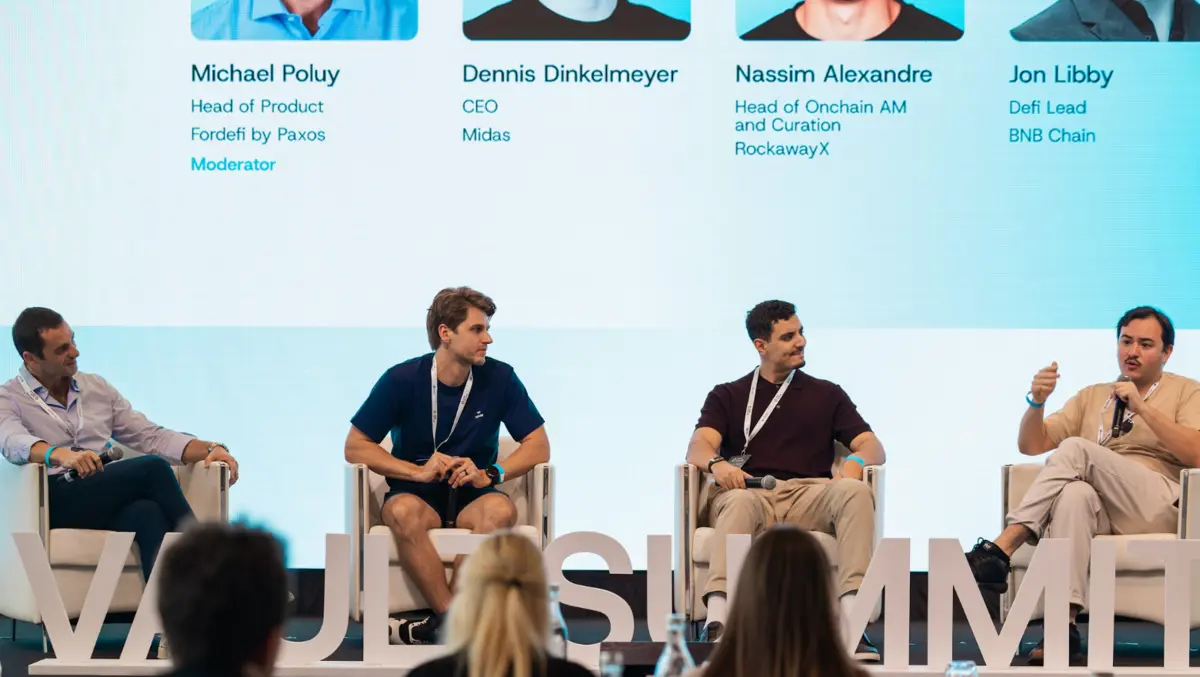
Vault Summit in Singapore spotlights onchain finance
Mon, 12th Oct 2026 (Today)
DigiFT and Morpho convened Vault Summit in Singapore to discuss onchain vault infrastructure and capital strategies, bringing together executives from traditional finance and digital asset firms.
Speakers focused on institutional asset management, tokenised assets and the risk frameworks market participants say are needed as onchain finance develops. Companies represented included S&P Global Ratings, Bitwise, Circle, Standard Chartered, Franklin Templeton, Fidelity International, UBS and Hanwha Investment & Securities.
One clear theme was established financial institutions seeking practical routes into digital assets rather than treating the sector as a niche market. Jonathan Man, Head of DeFi Strategies at Bitwise Asset Management, said firms were examining both new products and new distribution models.
"Institutions are now trying to figure out how to access interesting products, how to build them, and how to use the technology to distribute their products. When you're stuck in the crypto ecosystem, you may feel bearish, but when you take a step back, you realise this is only starting to increase and pick up," Man said.
Giselle Lai, Director of Digital Asset Strategy, APAC, at Fidelity International, described blockchain-based market development as a progression from holding assets to earning yield and then putting assets to work through onchain applications. Man also pointed to the speed of product development in digital assets.
"This is the age of fast finance for us, where we can create products very quickly and iterate very fast," he said.
Risk focus
Risk assessment was a central part of the discussion, particularly after S&P Global Ratings introduced its Vault Risk Assessment framework for digital asset lending vaults. Jim Wiemken, Head of Global Ratings Services at S&P Global Ratings, said the group was developing analytical tools for a changing market rather than reusing older models.
"S&P Global Ratings is not watching this market from the sidelines. What is consistent across all of our initiatives is that we're not simply applying existing products to new markets. We're creating new forms of analytical transparency for new forms of financial infrastructure," Wiemken said.
He said the group's approach was to build benchmarks and frameworks as the market evolves. "This is how we continue to move the market, not by predicting every turn and every innovation, but by innovating alongside markets themselves, developing new benchmarks, new analytical frameworks, and new forms of risk transparency to help markets grow responsibly," he said.
Andrew O'Neill, Managing Director and Digital Assets Analytical Lead at S&P Global Ratings, said vault assessments extend the firm's work from stablecoins and tokenised funds into the asset management layer of onchain finance.
"We started doing stablecoin risk assessments three years ago now. We've been doing ratings on tokenised funds on the asset side, and having done the asset side and the cash side of onchain finance, this week we've announced vault risk assessments, so we're starting to bring that risk analysis to the asset management layer of onchain finance as well," O'Neill said.
How vaults work
Several speakers argued that vault structures could bring more discipline to onchain investing by embedding rules directly into the product. In a discussion with Henry Zhang, Founder and Group CEO at DigiFT, Wayne Hsu, Executive Vice President at KGI Financial, contrasted vaults with traditional mandates.
"The vault is a strategy wrapper with rules built in. Traditionally, for asset managers, the mandate lives in legal documents and can only be enforced by after-the-fact monitoring. In the vault, however, constraints on leverage, concentration, counterparties or rebalancing can be coded and enforced in real time," Hsu said.
He added that "as underlying asset managers, we want to create more value to the underlying asset holders" and that "trust is built in layers."
Zhang said the market for tokenised real-world assets was moving from simple issuance to use cases built around the tokens themselves. "RWA is moving from 1.0 to 2.0. With 1.0, we bring assets onchain, tokenising them, but now, as we're quickly coming to Phase 2, it's about using the tokens. Risk curators are key partners coming in to create asset portfolios. On one hand, they do the asset management onchain, but more than that, they can cross platforms," he said.
Jasmine Jia, Head of Tokenisation Ecosystem at Fidelity Digital Asset Management, said the new language around curation still maps closely to established investment management practice. "It's a new terminology that's different from asset management. However, by characteristics, it's very similar to the traditional role of an asset manager," Jia said.
Operational demands
Other sessions focused on the practical barriers institutions face when moving activity onchain. Insung An, CDO at Hanwha Investment & Securities, outlined the controls his firm requires for trade execution in round-the-clock token markets.
"First, rules need to be checked before the trade; if it breaks our risk policy, it would not be executed. Second, a full record must be made, so that when our auditor or regulator asks, we can show them a record without explaining it from memory. Third, there must be a clear authority during emergencies since token markets are trading 24/7; if a price feed fails or something happens, if you need to ask who holds the key, it's too late," An said.
He added: "Code is only the execution engine; onchain lowers the repetitive cost, but it never takes away the responsibility."
Matt Enslin, Senior Manager of Arc and Global Ecosystem at Circle, pointed to another obstacle for larger companies building products on blockchain networks. "I think that the number one challenge we've seen from enterprises historically was gas having to hold ETH or SOL or other volatile crypto assets basically makes the accounting and treasury management of building onchain products nearly impossible," Enslin said.
On market structure, Paul Frambot, Co-Founder and CEO at Morpho, said large-scale onchain lending would require many more lending markets and specialist risk managers. "If you're truly ambitious about moving lending and credit onchain, it is a necessity that you're going to have tens of thousands of lending markets... if you want to underwrite 8 billion people, you're going to need an army of risk curators that are going to source risk," Frambot said.
He also said vaults were designed to simplify access to fragmented markets. "Markets alone are a mess to interact with... I can't imagine a user interacting with Morpho and having to decide across 4,000 different markets. The whole reason why we came up with the idea of building vaults ourselves is basically that we needed more capital aggregation to solve the problem of isolation," he said.
In the final panel, institutional participants and digital asset specialists returned to the efficiency argument. Evgeny Gokhberg, Founder at Re7 Capital, said "vaults are a much more efficient wrapper... you can achieve a 10x or 100x cost savings in back office and backend infrastructure." Chetan Karkhanis, Lead of Digital Asset Partnerships at Franklin Templeton, added: "the blockchain is the single source of truth; there is no redundant digital twin. That's how you get the cost savings."